Dallas–Fort Worth 401(k) and retirement plan advisor
A 401(k) advisor in Dallas helps an employer compare plan types, define which provider carries which responsibility, evaluate investments and fees, coordinate implementation, and build an ongoing review process. WealthPlan works with Dallas–Fort Worth employers on those decisions within the scope of a written engagement, led by Wyatt Behlen, CRPS®.
What brought you here?
Setting up a first plan
Employers who want to set up a 401(k) in Dallas usually start here. Compare plan types, eligibility, payroll integration, any required employer contributions, administration, investments, and possible federal startup credits before selecting a structure.
Reviewing an existing 401(k)
Organize the plan’s services, fees, investment responsibilities, participant experience, and governance records before deciding whether a change is warranted. A review can confirm the current arrangement as easily as it can prompt a change.
Coordinating a more complex design
Map ownership, related entities, workforce data, existing plans, and provider roles before evaluating pooled arrangements or a cash balance plan alongside the 401(k).
What does a retirement plan advisor do for a Dallas employer?
The work begins with the employer’s objectives and workforce, not a product list. A 401(k) consultant’s role should be stated in writing and coordinated with the plan’s other professionals, because most of what a plan needs is performed by several firms at once.
Frame the plan-design questions
Clarify who should be eligible, whether employee deferrals and employer contributions are desired, how turnover and compensation patterns affect the design, and which administrative responsibilities the employer can realistically support.
Define fiduciary and provider roles
Identify which decisions remain with the plan sponsor and which services are assigned to an investment adviser, recordkeeper, third-party administrator, trustee, payroll provider, attorney, accountant, or auditor. Gaps between providers are where operational problems usually begin.
Compare proposals on the same basis
Review services, contracts, compensation, investment options, participant support, data responsibilities, transition work, and termination terms using a consistent scope. Two proposals written to different scopes cannot be compared on price.
Build an ongoing review process
Document how the employer will monitor services, expenses, investment responsibilities, participant communications, and open operational items after implementation. The review process, not the launch, is what a plan sponsor is judged on over time.
Should a Dallas small business choose a 401(k), SIMPLE IRA, or SEP?
These arrangements solve different problems. The table below is a starting point only; eligibility, contribution, testing, reporting, and tax rules require current plan-specific review.
| Plan type | How money generally enters | Questions to resolve |
|---|---|---|
| 401(k) | Employee salary deferrals and, depending on design, employer contributions. | Eligibility, testing or safe-harbor design, vesting, investments, payroll integration, Form 5500, participant disclosures, and fiduciary roles. |
| SIMPLE IRA | Employee salary reductions plus required employer matching or nonelective contributions. | The 100-employee eligibility rule, the required employer contribution formula, calendar-year timing, the IRA structure, and restrictions on maintaining another plan. |
| SEP | Employer contributions to SEP-IRAs; employees do not make salary deferrals to the SEP. | Which employees must be covered, the contribution formula, treatment of related businesses, and whether the employer wants employee salary deferrals or a more flexible qualified-plan design. |
For a small business 401(k) in Dallas, the design question that comes up most often is whether to use a safe harbor 401(k). A safe harbor design commits the employer to a specified contribution formula in exchange for relief from certain annual nondiscrimination testing. Whether that trade is worth making depends on the workforce, the compensation pattern, expected participation, and how much administrative complexity the employer wants to carry, so it should be modeled rather than assumed.
A cash balance plan is a defined benefit plan with actuarially determined funding. It may be evaluated alongside a 401(k) only after ownership, related entities, workforce data, cash-flow durability, existing plans, and provider responsibilities are understood. Practices and closely held businesses weighing that route can start with our guide to cash balance plans for Texas business owners.
How do 3(21) and 3(38) investment roles differ?
Investment advice
The adviser recommends. The employer decides. An adviser may make investment recommendations, but the responsible plan fiduciary keeps the authority to act on them or not. The agreement should state which recommendations the adviser provides and which decisions stay with the employer.
Discretionary investment management
The manager decides, within limits the agreement sets. A properly appointed investment manager may accept discretionary authority for the investment responsibilities defined in the agreement, which is what employers looking for a 3(38) investment manager in Dallas usually want: investment selection and monitoring off an internal committee’s desk. One duty does not transfer. The sponsor still must prudently select and monitor that provider.
How do you switch 401(k) providers or advisors?
A change of provider or adviser is a project with a sequence, and most of the difficulty sits in the data rather than the decision. Employers who want to switch 401(k) providers in Dallas generally work through five steps.
-
1
Establish what the current arrangement actually is
Collect the plan document and adoption agreement, service agreements, recent fee disclosures, investment reports, the most recent Form 5500, testing results, and any correction history. Confirm which provider performs each function today, including the ones no contract clearly assigns.
-
2
Define what the change is meant to fix
Cost, service, investment responsibility, participant experience, payroll integration, and governance support are different problems with different answers. Some can be resolved with the existing recordkeeper and third-party administrator, which is worth establishing before a search begins.
-
3
Run a same-scope comparison
Ask each candidate to respond to one written scope covering services, compensation, investment responsibilities, data handling, participant support, conversion work, and termination terms. A proposal that omits a service is not cheaper than one that includes it.
-
4
Plan the conversion before signing
Identify blackout timing, payroll file changes, outstanding loans, distributions in progress, beneficiary records, participant notice requirements, and who is responsible for each item on each side. Conversion errors are usually scheduling and data problems, not investment problems.
-
5
Document the decision and set the monitoring calendar
Record the reasons for the change, confirm contracts and responsibilities, assign implementation tasks, and establish how the new arrangement will be reviewed going forward. Legal, tax, actuarial, administrative, and payroll questions raised along the way should be routed to the appropriate professional rather than left open.
What should a Dallas employer compare before selecting a plan or provider?
The Department of Labor says selecting a service provider is a fiduciary act. A documented comparison works best when each provider responds to the same scope.
Plan and workforce fit
Who is eligible, who is expected to use the plan, which related entities or employee groups belong in the analysis, and what the employer wants the plan to accomplish.
Services and responsibility
Who handles plan documents, testing, filings, payroll data, participant notices, distributions, investment decisions, cybersecurity, education, and correction support.
Fees and compensation
Direct and indirect compensation, who pays each amount, whether fees change with assets or participants, investment expenses, one-time transition charges, and termination costs. A 401(k) fee benchmark is only useful when the services behind each number are the same; comparing a bundled quote to an unbundled one without normalizing scope produces a difference that is not a saving.
Contract and transition terms
Service standards, data ownership, implementation responsibilities, conversion timing, renewal and termination provisions, and what happens if the employer changes providers later.
Participant experience
Enrollment, education, digital access, call support, investment information, beneficiary processes, and support for common participant transactions.
Ongoing governance
Meeting cadence, reports, issue tracking, investment review, fee review, provider monitoring, documentation, and the people responsible for follow-through.
Up to
$5,000
for each of 3 tax years
Eligibility and calculation required
Could federal tax credits offset some startup costs?
Current IRS guidance says an eligible small employer may be able to claim a credit of up to $5,000 for each of three tax years for qualified costs of establishing or administering an eligible plan and educating employees about it.
The amount and eligibility depend on employee count, non-highly compensated employee participation, prior-plan history, controlled-group and predecessor rules, eligible costs, and the timing election. For employers with 50 or fewer employees who received at least $5,000 in compensation in the preceding year, the startup-cost percentage may be 100%; for 51–100 such employees, it remains 50%, in each case subject to the statutory calculation and cap. A separate $500 annual credit may apply for three years when an eligible automatic-contribution arrangement is first included and maintained.
These credits are not automatic, and the same startup expense cannot support both a deduction and the credit. Confirm eligibility, calculations, elections, and current Form 8881 instructions with the employer’s qualified tax professional before relying on a credit.
Source checked 2026-08-26: IRS: Retirement plans startup costs tax credit
What happens when a Dallas employer starts a plan review?
Four steps, and we do the work in each one. You supply what you have, we organize the rest, and you keep every decision.
-
STEP 1
We start with the decision
First plan, review of an existing one, provider comparison, or a more complex design. We settle which of those you are actually making, because each one calls for a different review.
-
STEP 2
We tell you what to pull
Ownership and related entities, an employee census, plan and service agreements, recent fee disclosures, investment information, payroll details, and any issues you already know about. Send what you have and we will chase the gaps.
-
STEP 3
We build the comparison
We put the alternatives side by side on the same assumptions, identify which professionals your situation needs, and write down the legal, tax, actuarial, administrative, and payroll questions that still need an answer.
-
STEP 4
You decide, we document
The choice is yours. We record the reasons behind it, confirm contracts and responsibilities, assign the implementation tasks, and set the monitoring calendar before launch or conversion.
Who would a Dallas employer work with?
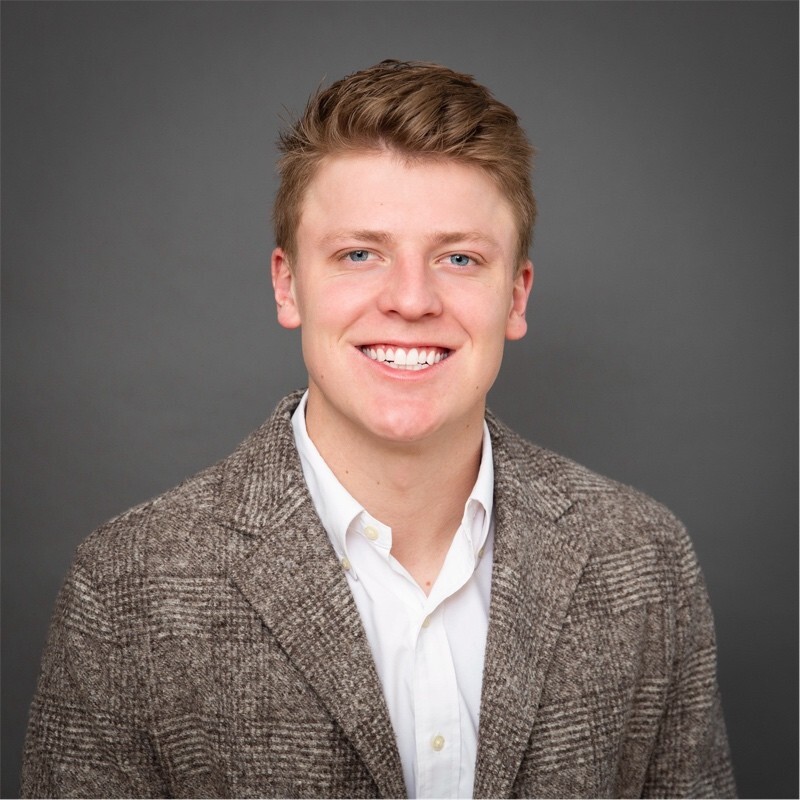
Wyatt Behlen, CRPS®
Advisor & Retirement Plan Specialist
Wyatt is based in Dallas and serves employers throughout the DFW area. He holds the Chartered Retirement Plans Specialist (CRPS®) designation and a Series 65 license, and works with plan sponsors on design, implementation, and ongoing plan management. Employers looking for a Dallas 401(k) specialist to sit in a committee meeting, work through a fee comparison, or coordinate a conversion would work with Wyatt and the team that supports him.
Serving Dallas–Fort Worth employers as a regional service area. No street address is published.
Does Texas require my business to offer a retirement plan?
No. Texas does not operate a state-facilitated retirement savings program, so there is no state requirement to sponsor a plan or enroll in a state program. For a Texas employer, a 401(k) is a business decision rather than a compliance one, which changes the question from whether you must act to whether the plan earns its cost.
One exception worth checking
If you employ people outside Texas, another state’s rules may still reach you. Several states do require covered employers either to enroll in a state program or to offer a qualifying private plan, and those requirements follow the employee rather than your headquarters. DFW businesses with remote or multi-state staff should review each state’s requirements with counsel, and a qualifying 401(k) is generally one of the ways a covered employer satisfies them.
Why do Dallas–Fort Worth employers sponsor a plan anyway?
With no mandate forcing the decision, the four reasons below are what usually carry it.
An employer contribution is possible
A 401(k) can be designed to include a matching or nonelective employer contribution, including through a safe harbor structure. Whether to fund one, and how much, stays with the employer.
Contribution limits are higher
Annual employee deferral limits for a 401(k) are set well above IRA contribution limits, and the plan can also receive employer contributions within the applicable annual limits. For owners and higher earners this is often the deciding factor. Current-year limits should be confirmed against the applicable IRS figures for the plan year in question.
Startup credits may apply to a plan
The federal startup credits described above relate to establishing and administering an eligible employer plan. An employer weighing whether to sponsor one should have its tax professional confirm what would and would not be creditable in its own facts.
It is a hiring and retention line item
In a labor market as competitive as Dallas–Fort Worth, the plan is part of what a candidate compares. Design choices that show up in that comparison include the match formula, eligibility waiting period, vesting schedule, and how easy the plan is for a participant to use.
None of the four is a reason to sponsor a 401(k) on its own. Together they are usually why a Texas employer under no obligation to act decides to build a plan anyway.
Dallas retirement plan advisor FAQs
Does a small Texas business have to start a 401(k)?+
Not under a Texas state mandate. This page does not assume one. Federal rules govern a 401(k) once an employer chooses to establish one, and employers with workers in other states should separately review those states’ requirements with counsel. The practical question for most DFW businesses is not whether they are required to sponsor a plan but whether one fits the workforce, the budget, and the administrative capacity they actually have.
We have employees in other states. Does that change anything?+
It can. Several states require covered employers either to participate in a state-facilitated program or to offer a qualifying private plan, and those requirements generally follow where the employee works rather than where the business is headquartered. A qualifying 401(k) is commonly one of the ways a covered employer satisfies them. Review each state’s rules, thresholds, and deadlines with counsel before assuming a Texas address settles the question.
Do you meet in person with Dallas–Fort Worth employers?+
Yes. We come to you. Meetings are held at your workplace or virtually, depending on what the discussion calls for, and committee meetings and participant education sessions are done on site. Dallas–Fort Worth is served as a regional service area and no street address is published.
Are retirement plan startup tax credits guaranteed?+
No. Eligibility and the amount depend on current tax law and employer facts. The employer’s qualified tax professional should confirm the current Form 8881 rules, controlled-group treatment, eligible expenses, elections, and interaction with deductions before a credit is claimed or included in a budget.
Does hiring a retirement plan advisor remove the employer’s fiduciary responsibility?+
No. An employer may allocate responsibilities and engage fiduciary service providers, but the responsible plan fiduciaries retain duties that include prudently selecting and monitoring providers and following the plan documents. The written agreement should state each party’s role.
Can WealthPlan serve as the plan administrator or recordkeeper?+
Unless separately and expressly engaged, WealthPlan does not act as the plan administrator, trustee, recordkeeper, third-party administrator, attorney, accountant, or auditor. The service team and written agreements must identify who performs each function.
How should an employer compare retirement plan fees?+
Compare the complete services and compensation on the same basis. Include direct charges, indirect compensation, investment expenses, asset- or participant-based fees, one-time costs, termination charges, and who pays each amount. A lower quoted price is not meaningful if the scope differs.
Related Dallas and Texas retirement-plan resources
Bring the plan decision into focus
A first conversation can clarify the decision, the facts that belong in the review, and the specialists who may be needed. It does not commit the employer to a plan design, provider, or engagement. You can also see WealthPlan’s retirement plan services for employers for the broader service framework, or our guide to starting a small-business 401(k) in Dallas–Fort Worth.
Available services, the responsible WealthPlan entity, fiduciary capacity, and fees depend on the employer, plan, professionals involved, written engagement, and applicable disclosures. This page provides general education, not individualized investment, tax, legal, actuarial, or accounting advice. Contacting WealthPlan does not create an advisory relationship. Do not send account numbers, Social Security numbers, tax returns, employee census data, or other sensitive documents through a general website form or ordinary email.