
Before You Move Your 401(k), Understand What The Move Could Cost
Leaving a Denver-area employer or retiring can turn an old 401(k) into a decision you make only a few times in life. We help people across the Denver metro compare the four broad paths using the former plan, any eligible new plan, and the rest of the financial picture before anything moves.
Start your rollover review
$6.1B
Combined client assets1
37
Years in business2
13
States3
Denver rollover guidance
Connect the old account to the decision in front of you
A rollover is not a destination by itself. The review should connect the former plan to your new job, retirement timing, investment approach, taxes, access needs and the people helping you make the decision.
Start with the Denver team
Meet the WealthPlan professionals serving Denver-area households and see the established Colorado practice behind the conversation.
Keep employer and personal paths separate
Individuals comparing an old 401(k) follow this rollover path; employers evaluating a workplace plan use the separate Denver retirement-plan advisor page.
Coordinate the account with the full plan
Investment, tax, cash-flow and retirement-income questions can be considered together while qualified tax or legal professionals remain responsible for their advice.
What You Can Actually Do With An Old 401(k)
Most people consider four broad paths for a former plan. What separates them is what you pay, what you control, and what you leave behind on the way out.
Leave It Where It Is
If the former plan allows it, doing nothing is a real option. Institutional pricing, a familiar menu, and workplace-plan protections are worth something.
Check first: whether the plan still services former employees, and what it charges them.
Move It To Your New 401(k)
If your new employer’s plan accepts rollovers, one account is easier to manage than two. The new plan is not automatically the better one.
Check first: the new plan’s investments, fees, services, and withdrawal rules.
Roll It Into An IRA
An IRA opens up the investment universe and lets the account be managed alongside the rest of your plan. It carries a different fee and protection profile.
Check first: total cost of the IRA against total cost of the plan, advisory fees included.
Take The Money In Cash
Cashing out can trigger taxes, possible penalties, and the loss of future tax-deferred growth. It is the one path that cannot be undone.
Check first: the full tax cost before requesting a payment.
20%
Federal withholding
A Check Made Out To You Is Not A Rollover
In a direct rollover, the eligible payment goes to the receiving plan or IRA and generally is not subject to federal withholding. An eligible employer-plan payment made to the participant is generally subject to 20% withholding, and completing a full 60-day rollover may require replacing the withheld amount out of pocket.
Source: IRS, Rollovers of retirement plan and IRA distributions
Compare All Four Before You Decide
The review begins with your plan documents, not with a destination already chosen for the money. Four things get examined before any recommendation is made.
Understand What You Own
We review the balance, investments, fees, account types, employer stock, loans, and the rules of your old plan so important details do not get missed.
Compare The Real Costs
We put the costs of staying in the plan, moving to a new one, and using an IRA on the same page, including advisory fees when they apply.
Look Beyond Investments
Convenience matters, but so can withdrawal choices, advice, plan loans, beneficiary rules, creditor protections, and how the account fits with the rest of your finances.
Catch Tax Issues Early
Employer stock, an outstanding loan, Roth money, after-tax contributions, your age, and when you left the job can change the analysis. We identify questions that need tax or legal input before money moves.
Bring the statement. See the plan’s costs and trade-offs more clearly.
A focused first conversation can organize the four paths and the information needed to compare them.
Request a rollover reviewA Side-By-Side Look At The Choices
There is no automatic winner. Focus on the differences that will actually affect how you save, invest, and use the money.
| Factor | Employer-plan questions | IRA questions |
|---|---|---|
| What you pay | Plan and investment fees, transaction costs, and charges for advice or special services. | Custody, investment, transaction, and advisory fees, including how the advisor is paid. |
| Investment help | The plan’s menu, managed options, education, and support. | A wider range of investments and the level of planning or advice you choose. |
| Using the money | The plan’s rules for withdrawals, installments, loans, and beneficiaries. | IRA withdrawal, conversion, beneficiary, and account-management choices. |
| Important protections | Federal workplace-plan protections and tax rules that may apply only inside a plan. | The federal or state protections that apply to the IRA and any plan-only features you would leave behind. |
| Keeping things organized | Whether your new plan can accept and combine the account with current savings. | How the IRA will fit with your other accounts, tax planning, and ongoing advice. |
Rollover Decision Checklist
You do not need every answer before the first conversation. These are the items that turn a general discussion into a useful comparison.
Your Latest Statement
This shows the balance, current investments, types of money in the account, employer stock, and any outstanding loan.
Your Plan Information
Fee and investment disclosures, the plan summary, and any distribution packet help us see what you have today.
Your Other Accounts
A current 401(k), existing IRAs, pensions, and taxable investments can change the value of consolidation and coordination.
What Matters To You
Tell us about your timeline, expected withdrawals, need for advice, beneficiary goals, tax concerns, and preference for simplicity or flexibility.
A Clear Comparison
We organize the choices, costs, services, key trade-offs, and any conflicts so you can see why one path may fit better than another.
A Transfer Plan
If you decide to move the account, we help clarify the receiving account, paperwork, delivery process, investment timing, and follow-up.
Bring What You Have. We Will Tell You What Is Missing.
A first conversation is a comparison, not a commitment. If staying in the plan is the better answer, that is what the review will say.
How The Transfer Process Works
-
STEP 1
Open Or Confirm The Destination
Verify that the receiving IRA or employer plan can accept each type of money before requesting a distribution.
-
STEP 2
Request A Direct Rollover
When available and appropriate, instructions generally direct the former plan to pay the eligible amount to the receiving plan or IRA rather than to the participant.
-
STEP 3
Track Assets And Documents
Monitor any check or electronic transfer, retain confirmations, and avoid assuming the process is complete until the receiving account posts the assets correctly.
-
STEP 4
Review The Completed Account
Confirm registration, money types, beneficiaries, cash or investment status, fees, and any remaining balance in the former plan.
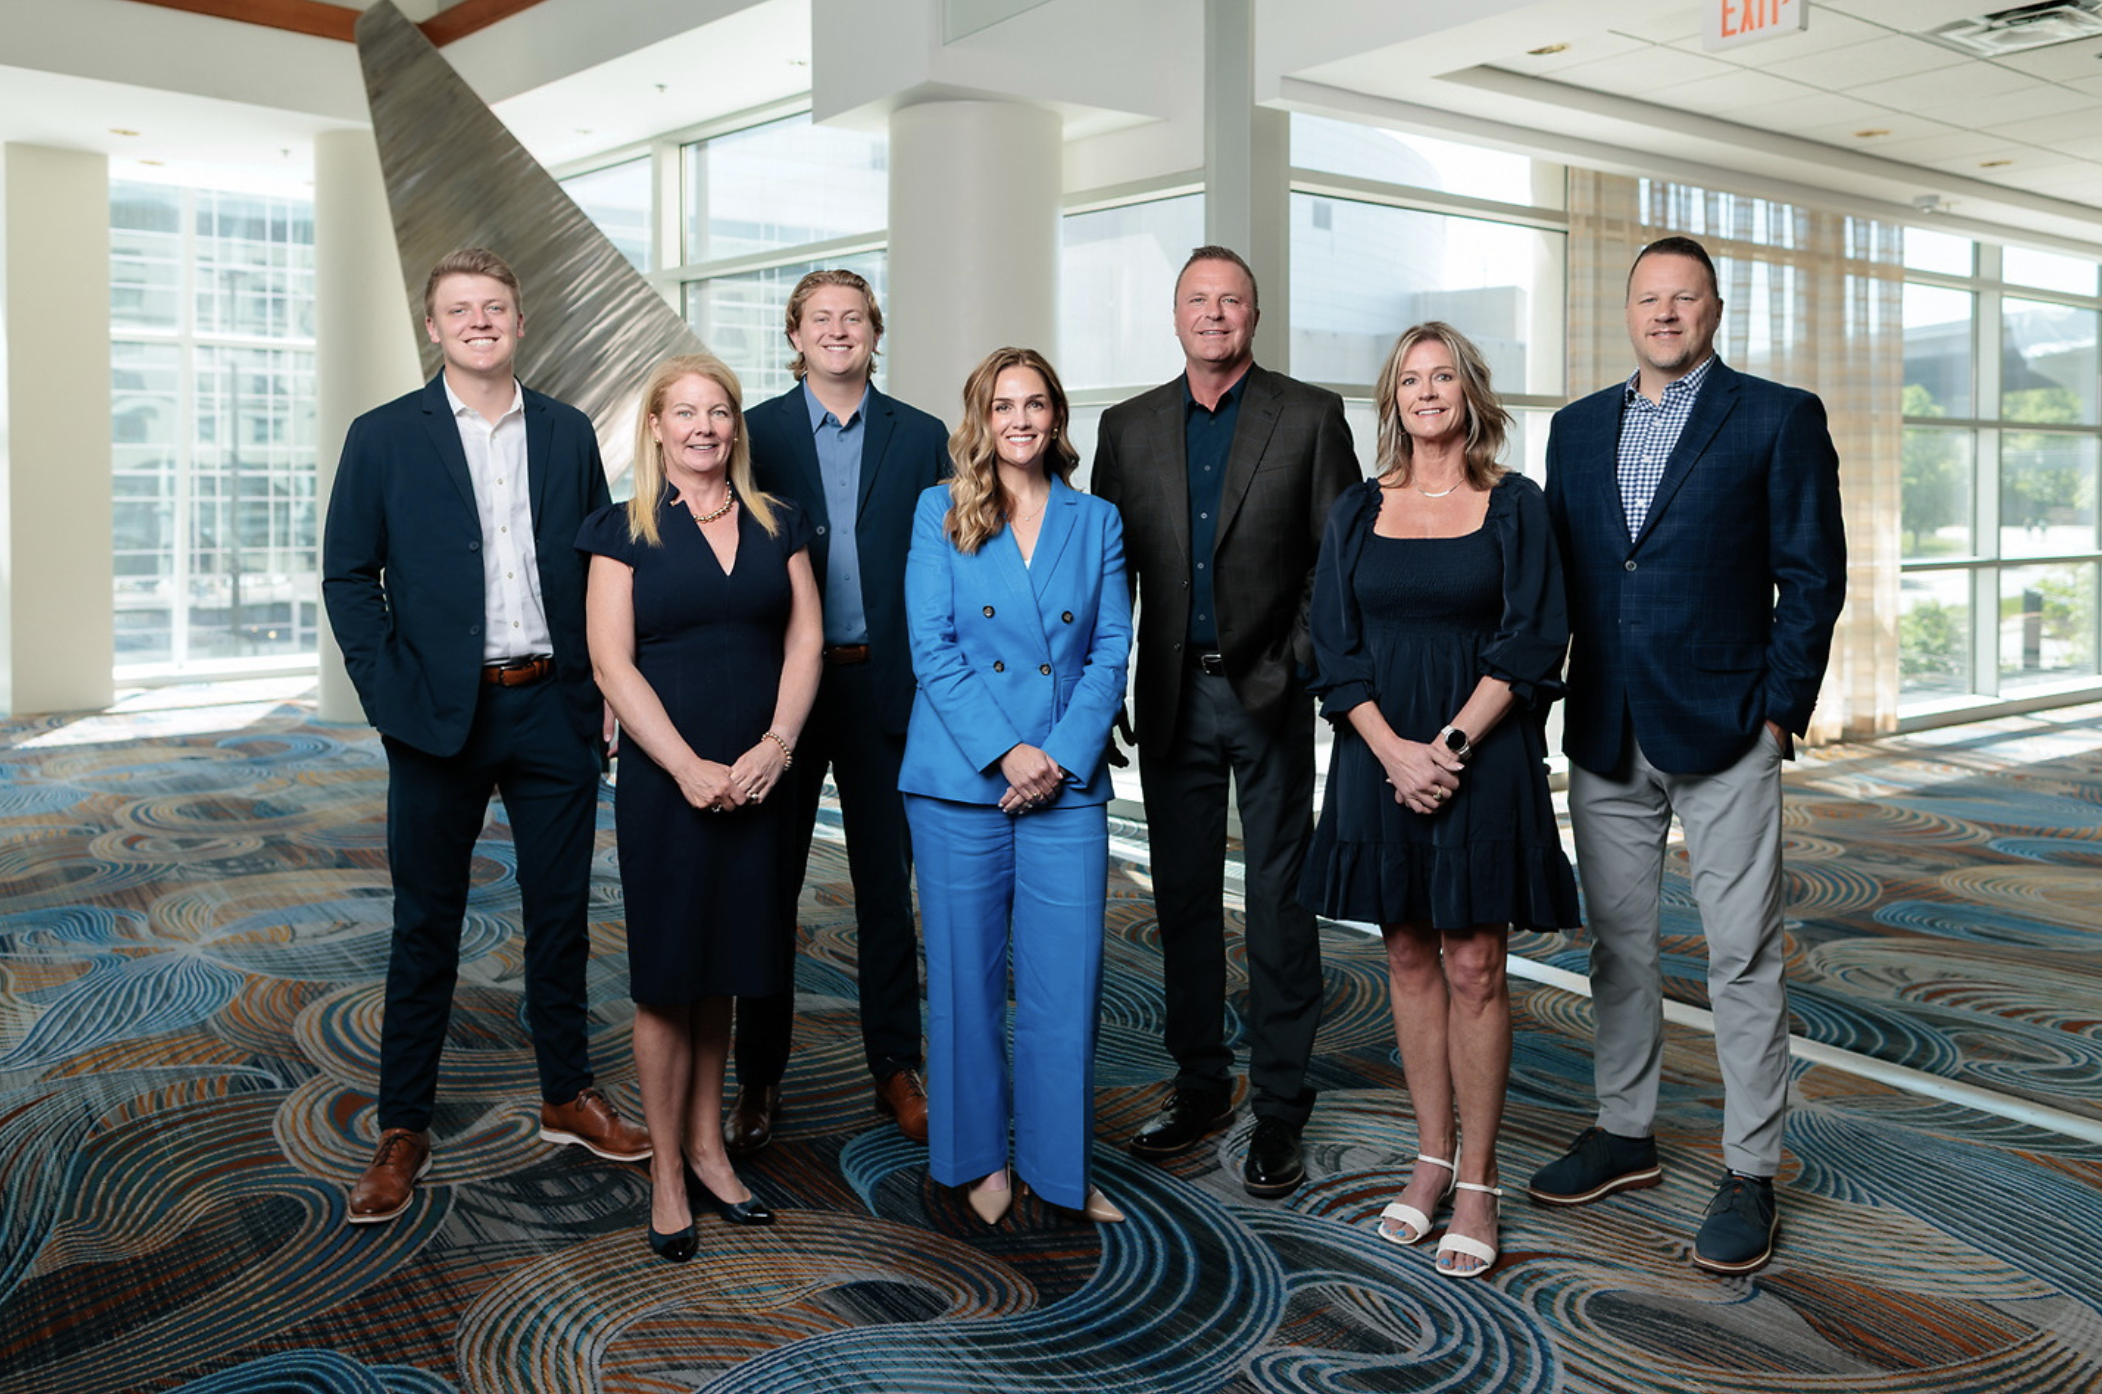
Meet The Retirement Team
We deliver personalized, boutique-level support to each client. Every plan receives the attention it deserves.
Access to a team of experienced wealth advisors for personalized guidance, plus enrollment and rollover assistance to support new participants and transitions.
38
Advisors nationwide4
62
Support staff4
1989
Established2
Denver 401(k) Rollover FAQs
Should I roll my old 401(k) into an IRA?+
Not automatically. An IRA is one option. Compare the former plan, any eligible new employer plan, an IRA, and a distribution using actual costs, services, investments, protections, tax issues, and account features before deciding.
What does a 401(k) rollover review cost?+
There is no universal price. Compare the costs already paid in the plan with any IRA custody, investment, transaction, and advisory fees. WealthPlan services and compensation depend on the written agreement and applicable disclosures, which should be reviewed before proceeding.
How long does a 401(k) rollover take?+
There is no fixed timeframe. Timing depends on the former plan, receiving institution, account and asset types, required forms, delivery method, and whether information is complete. Ask both institutions for their current processing steps and estimates, then track the transfer through final posting.
Is a direct rollover different from a check made payable to me?+
Yes. In a direct rollover, the eligible payment is made to the receiving plan or IRA and generally is not subject to federal withholding. An eligible employer-plan payment made to the participant is generally subject to 20% withholding, and completing a full 60-day rollover may require replacing the withheld amount.
Can I move an old 401(k) into my new employer’s plan?+
Possibly. A new plan may accept eligible rollovers but is not required to. Confirm its acceptance rules, investments, fees, services, distribution provisions, and treatment of each account source before requesting the transfer.
When should I consult a tax or legal professional before rolling over?+
Plan-specific review is especially important when the account includes employer stock, a loan or loan offset, after-tax or Roth money, required minimum distributions, a recent separation near age 55, divorce or beneficiary issues, or potential creditor-protection concerns.
Related Rollover And Denver Resources
Compare The Paths Before Moving The Account
A first conversation can identify the available accounts, missing records, costs, features, conflicts, and tax or legal questions that belong in the review. It does not commit you to a rollover or advisory engagement.
Request a rollover reviewThis page provides general education and is not an individualized rollover recommendation or tax, legal, or accounting advice. A rollover recommendation, if provided, depends on the investor’s circumstances, the alternatives reasonably available, current plan and account information, applicable law, and a written advisory engagement. WealthPlan’s services, responsible entity, fiduciary capacity, and compensation depend on the agreement and disclosures. Moving assets to an advisory account may increase compensation paid to WealthPlan. Contacting WealthPlan does not create an advisory relationship. Do not send account numbers, Social Security numbers, tax returns, or other sensitive records through a general website form or ordinary email.
Disclosures
1 Combined client assets across affiliated businesses as of 12/31/2025. This figure includes assets associated with WealthPlan Partners and WealthPlan Investment Management, including assets under management, assets under advisement, and certain retirement plan and brokerage assets for which affiliated firms provide advisory, consulting, or planning services. Not all such assets constitute “regulatory assets under management” as defined by the SEC.
2 WealthPlan Group is a trade name under which affiliated entities conduct business. The firm has operated under multiple brand names over time. WealthPlan Group was founded in 1989. References to the firm’s history or years in business reflect the organization’s history since 1989, including predecessor businesses and prior brand names
3 Represents the number of states in which WealthPlan maintains office locations / personnel as of 12/31/2025. This statistic does not imply service availability in all jurisdictions for all representatives or entities
4 The number of advisors and support personnel reflects firm staffing as of 12/31/2025 and may fluctuate over time.
Primary sources
Rollovers of retirement plan and IRA distributions
Internal Revenue Service. Checked 2026-08-24.
Switching Jobs
U.S. Securities and Exchange Commission. Checked 2026-08-24.
Choosing the Right Person to Give You Investment Advice
U.S. Department of Labor. Checked 2026-08-24.
New Fiduciary Advice Exemption: PTE 2020-02 FAQs
U.S. Department of Labor. Checked 2026-08-24.